How to turn a simple credit line into a powerful tool for customer acquisition, retention, and competitive differentiation for B2B suppliers, distributors, and merchants.
Foreword
In professional distribution, wholesale, and B2B commerce, commercial relationships are no longer won on price or product assortment alone. Increasingly, they’re defined by a company's ability to finance purchases precisely when business customers need them.
This article demonstrates why credit limits should no longer be viewed simply as a risk management tool. They have become a powerful signal of trust, a sales accelerator, a customer retention lever, and a valuable source of commercial intelligence. When managed strategically, credit limits transform a financial constraint into a sustainable competitive advantage.
RollingFunds was built around this vision. Our Buy Now, Pay Later (BNPL) solution for deferred and installment payments enables suppliers, distributors, wholesalers, and B2B merchants to offer their business customers clear, tailored credit limits exactly when they’re needed—without assuming the credit risk or the operational complexity traditionally associated with trade finance.
This article is intended for both our current and future partners. It explores the strategic role of credit in driving B2B growth and illustrates how RollingFunds turns these principles into measurable business outcomes: more orders, stronger customer loyalty, and increased market share.
1. B2B Credit: An Underutilized Strategic Asset
In an increasingly competitive business environment, the ability to deploy financial resources strategically has become a decisive competitive advantage. Among the most powerful yet underused levers are credit limits. Far beyond their traditional role in cash flow management, they have evolved into a powerful commercial tool that drives revenue growth, accelerates customer acquisition, and strengthens long-term customer loyalty.
Six Reasons to Turn Credit into Commercial Growth Lever
- A signal of trust – Extending an appropriate credit limit strengthens long-term business relationships and encourages customers to place larger, more frequent orders.
- A cash flow optimization tool – Credit limits help smooth the timing gap between incoming and outgoing payments, improving working capital management for both suppliers and business buyers.
- A meaningful competitive advantage – In mature markets where products and pricing are often comparable, payment flexibility can be the deciding factor between two competing offers.
- A catalyst for market expansion – Attractive financing terms reduce purchasing barriers when launching new products, entering new markets, or acquiring new customer segments.
- A driver of customer loyalty – Increasing financing capacity for high-value customers rewards loyalty and encourages repeat purchasing over time.
- A valuable source of commercial intelligence – Credit utilization provides deep insights into purchasing behavior, enabling businesses to refine marketing campaigns, sales strategies, and customer segmentation.
When embedded within a broader commercial strategy, credit limits become far more than a financing mechanism. They enhance the buying experience, deepen customer relationships, and create a sustainable engine for long-term growth. That is precisely the role RollingFunds plays for its partners: transforming B2B credit from a financial function into a strategic growth platform.
2. The Psychology of Credit: What Drives Your Business Customers to Buy
Credit limits play a pivotal role in shaping B2B purchasing behavior. Far more than a risk management tool, they influence how businesses perceive their financial capacity, make investment decisions, and ultimately decide when and how much to buy. Understanding these psychological drivers enables suppliers and distributors to build more effective commercial strategies.
The Perception of Financial Capacity
When a business buyer is granted a higher credit limit, they gain a greater sense of financial flexibility. This increased purchasing confidence encourages larger orders and faster investment decisions. A contractor whose available credit increases from €5,000 to €10,000, for example, is far more likely to purchase new equipment or build inventory immediately rather than postponing the investment until sufficient cash becomes available.
Prudent Use Creates Confidence
Not every business customer fully utilizes their available financing. Many deliberately maintain a conservative approach to preserve liquidity and financial flexibility. Rather than diminishing the value of a credit facility, this behavior reinforces it. Simply knowing that financing is available provides reassurance and reduces purchase hesitation. Even if customers use only a fraction of their available credit, they are more likely to return to the supplier who provides that flexibility than to search for alternative vendors.
The Power of Flexible Payment Options
Business buyers are highly responsive to financing benefits, whether through deferred payment terms, installment plans, loyalty incentives, or promotional financing. Spreading the cost of a purchase over time significantly reduces the perceived financial burden at the point of sale. A tradesperson, for example, is much more likely to purchase a new machine today if the payment can be spread over several months instead of waiting until enough cash has accumulated.
Credit as a Competitive Signal
Credit conditions communicate more than financing—they signal trust. A supplier willing to extend a meaningful credit limit demonstrates confidence in the customer's business. In return, customers feel empowered to place larger orders, invest more aggressively, and grow with greater peace of mind. Over time, that confidence becomes associated with the supplier who made it possible, creating a powerful source of loyalty and competitive differentiation.
3. RollingFunds: Deferred and Instalment Payments Built for B2B
RollingFunds is a B2B Buy Now, Pay Later (BNPL) solution designed for suppliers, distributors, wholesalers, and merchants selling to professional customers —including tradespeople, SMEs, construction companies, industrial businesses, retailers, and hospitality professionals. Integrated seamlessly into existing purchasing journeys, both in-store and online, RollingFunds transforms every transaction into a smooth, secure, and frictionless financing experience.
How It Works
- At checkout, business customers can choose to pay later (30, 60, or 90 days) or spread payments over multiple installments (3, 4, 5, or 6 payments).
- RollingFunds instantly assesses the customer’s financing capacity through a single onboarding process and automated scoring, while assigning a personalized monthly credit limit.
- The supplier, distributor, or merchant receives immediate payment from RollingFunds, without waiting for the payment terms selected by the customer.
- RollingFunds manages credit limit monitoring and adjustments, payment reminders, and, when necessary, collections—allowing partners to stay focused on sales and customer relationships.
What This Changes for Your Business
- No credit risk on your balance sheet — RollingFunds finances the transaction and manages risk assessment on your behalf.
- Immediate cash collection — Preserve your cash flow while giving customers the payment flexibility they need.
- Higher average order values and purchase frequency — Driven by customers’ increased perceived purchasing capacity.
- A strong competitive differentiator — Stand out from competitors by offering an integrated financing solution as part of the buying experience.
- Consolidated purchasing insights — Leverage customer payment and purchasing behavior data to refine marketing campaigns and commercial strategies.
4. Turning Credit Limits into a Customer Loyalty Engine
In an increasingly competitive financial environment, strategically increasing credit limits can become a powerful customer retention lever. By recognizing and rewarding responsible financial behavior, suppliers can build stronger, long-lasting relationships with their customers—driving repeat purchases, deeper engagement, and increased referrals.
A Step-by-Step Approach
- Assess customer eligibility — Analyze payment history, purchasing patterns, and financial stability to identify customers who qualify for increased credit capacity.
- Personalize communication — Adapt messaging and offers based on each customer’s specific behaviors, needs, and business profile.
- Reward loyalty — Long-standing customers with a proven track record can benefit from more significant credit limit increases than new customers.
- Encourage responsible usage — Support customers with educational resources and guidance on how to effectively manage their available credit.
- Measure the impact — Track changes in purchasing behavior, payment performance, and customer engagement after each credit increase.
- Close the feedback loop — Collect insights from customers who received increased limits to continuously improve the strategy.
5. Credit Limits and Market Share Growth
In a highly competitive financial environment, the strategic management of credit limits has become a powerful lever for influencing market dynamics. By precisely calibrating the level of financing available to customers, suppliers, distributors, and B2B merchants can expand their customer base, strengthen loyalty, and increase market share..
The Impact on Purchasing Behavior
Higher credit limits encourage increased spending capacity. Distributors that raise credit limits for selected customers typically observe higher purchasing volumes, particularly during periods of increased demand—such as holiday seasons, promotional campaigns, or industry-specific peak cycles.
Risk Management as a Competitive Differentiator
Driving sales through credit also requires effective risk management. The most successful businesses rely on advanced scoring models and data-driven approaches to assess customer creditworthiness before adjusting financing capacity. In saturated markets, the ability to offer greater purchasing flexibility than competitors becomes a direct competitive advantage. Credit availability is no longer just a financial service—it becomes a key element of the customer value proposition.
Segmentation: The Foundation of a Targeted Strategy
Adapting credit limits according to customer profiles enables more precise commercial and marketing strategies. High-value customers, for example, can benefit from higher credit ceilings as part of a loyalty program, recognizing their contribution to revenue while encouraging continued engagement and repeat business.
6. Finding the Right Balance Between Risk and Opportunity
Strategic allocation of financial resources is a critical driver of growth acceleration and market expansion. However, achieving this potential requires a careful balance between risk management and value creation: credit limits must be ambitious enough to support sales growth while ensuring that businesses are not exposed to excessive financial risk.
The Four Pillars of a Controlled Credit Strategy
- Accurately assess risk — Consider payment history, financial strength, industry exposure, and the customer’s broader economic environment.
- Measure value creation potential — Credit should not only be viewed as a financial exposure; it is also a commercial investment that can generate additional sales, stronger relationships, and long-term loyalty.
- Adjust credit limits dynamically — Credit capacity should never be static. It must evolve based on customer performance, purchasing behavior, and changing market conditions.
- Segment customers according to their profile — Strategic accounts and long-standing customers may justify higher financing capacity based on their contribution and reliability.
The objective is not to provide the highest possible amount of credit, but rather to provide the right credit limit, to the right customer, at the right time. This balance transforms credit from a risk management constraint into a true competitive advantage.
7. What the Most Successful Credit Strategies Reveal
The most successful players in the B2B credit and deferred payment markets have achieved strong results by combining data intelligence, behavioral analysis, and personalization. These industry insights into credit limit management highlight the tangible potential that a solution like RollingFunds can unlock for its partners.
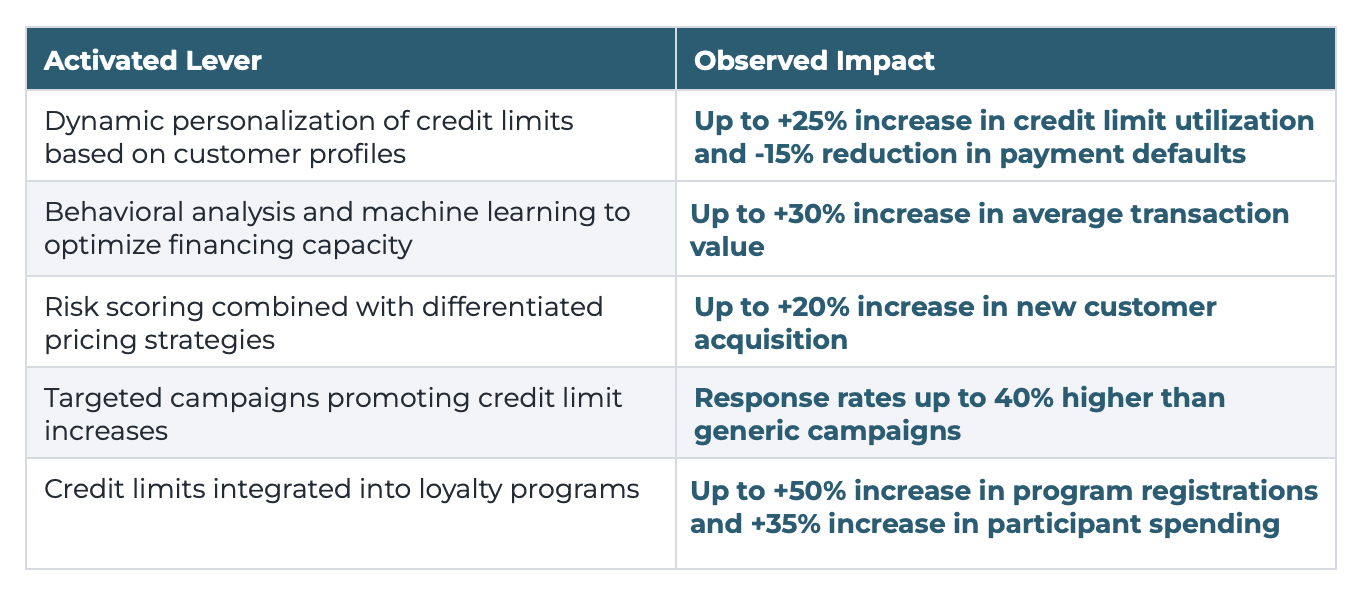
These results demonstrate that the most effective credit strategies rely on a careful balance between risk management and commercial growth. This is the principle embedded in the design of the RollingFunds platform: combining data analysis, real-time scoring, and personalized commercial activation to create a virtuous cycle where every credit decision generates value for all stakeholders.
8. Launching a Credit Limit Increase Campaign with RollingFunds
To be effective, a credit limit increase campaign must follow a structured, data-driven approach built around risk management and a personalized customer experience. RollingFunds natively integrates each of these steps into its platform.
Identify the Best Candidates (Eligibility) Through Data – RollingFunds continuously analyzes payment history, purchasing volume, financial health, and current credit limit utilization for each business customer. This enables the automatic identification of profiles most likely to benefit from increased financing capacity.
Assess Risk and Ensure Regulatory Compliance – Every credit limit increase is preceded by an integrated risk assessment process. This enables businesses to provide moderate increases to a broad customer base while reserving larger increases for the strongest credit profiles—while remaining aligned with applicable regulatory requirements.
Personalize Customer Communication – Through RollingFunds’ customer segmentation capabilities, each business customer can receive tailored communication based on their profile. This approach recognizes responsible financial behavior, strengthens customer engagement, and reinforces the relationship with your brand.
Automate Decisions Through Technology – RollingFunds’ scoring models automatically adjust credit limits based on available real-time data, reducing manual processes and accelerating financing decisions.
Measure Performance and Business Impact – The RollingFunds partner dashboard provides visibility into key performance indicators, including customer satisfaction, financing limit utilization rates, average order value evolution, purchase frequency, repayment performance, and default rates.
Encourage Adoption of New Financing Capacity – Credit limit increases can be integrated into your own commercial strategy by offering additional incentives, such as exclusive discounts, promotional offers, or rewards for first purchases made using the newly available financing capacity.
Train Your Teams – RollingFunds supports sales and customer service teams to ensure they fully understand the solution’s benefits, applicable conditions, and operational model. This knowledge is essential to driving adoption among professional customers and maximizing the commercial impact of the program.
9. Technology at the Core of the RollingFunds Platform
The combination of credit limits and technological innovation is fundamentally reshaping how B2B merchants engage with their professional customers and build long-term loyalty. The RollingFunds platform was designed around this vision: transforming credit from a static financial instrument into an intelligent, adaptive business capability.
The Technological Foundations of RollingFunds
- Personalized credit offers: Customers with consistent purchasing activity and strong payment behavior automatically benefit from adjustments to their financing capacity, aligned with their business profile.
- Behavioral and predictive analytics: RollingFunds anticipates periods of increased demand and enables temporary credit limit increases during peak business cycles, helping customers seize growth opportunities when they matter most.
- Dynamic risk management: Real-time monitoring allows credit limits to be adjusted proactively in response to economic changes or shifts in a customer’s financial situation.
- Integrated regulatory compliance: Credit approval processes are designed to adapt to applicable regulatory requirements without adding manual complexity for partners.
- Customer engagement: Each professional customer benefits from a dedicated account area where they can monitor and manage their available financing capacity in real time.
- Seamless integration across e-commerce, marketplaces, and physical points of sale: Financing capacity automatically adapts to purchase amounts, creating a smooth and consistent buying experience across every channel.
- Security and fraud prevention: Data encryption and advanced fraud detection mechanisms help secure every credit decision and limit adjustment.
With these foundations, a credit limit is no longer simply a predefined financial threshold. Within the RollingFunds ecosystem, it becomes a dynamic and interactive growth tool—helping partners strengthen customer relationships, accelerate sales, and address the increasingly complex operational and financial challenges of B2B commerce.
10. Why Choose RollingFunds?
Partnering with RollingFunds means giving your professional customers all the benefits of an intelligent credit strategy—without taking on the operational burden, financial exposure, or complexity traditionally associated with trade credit.
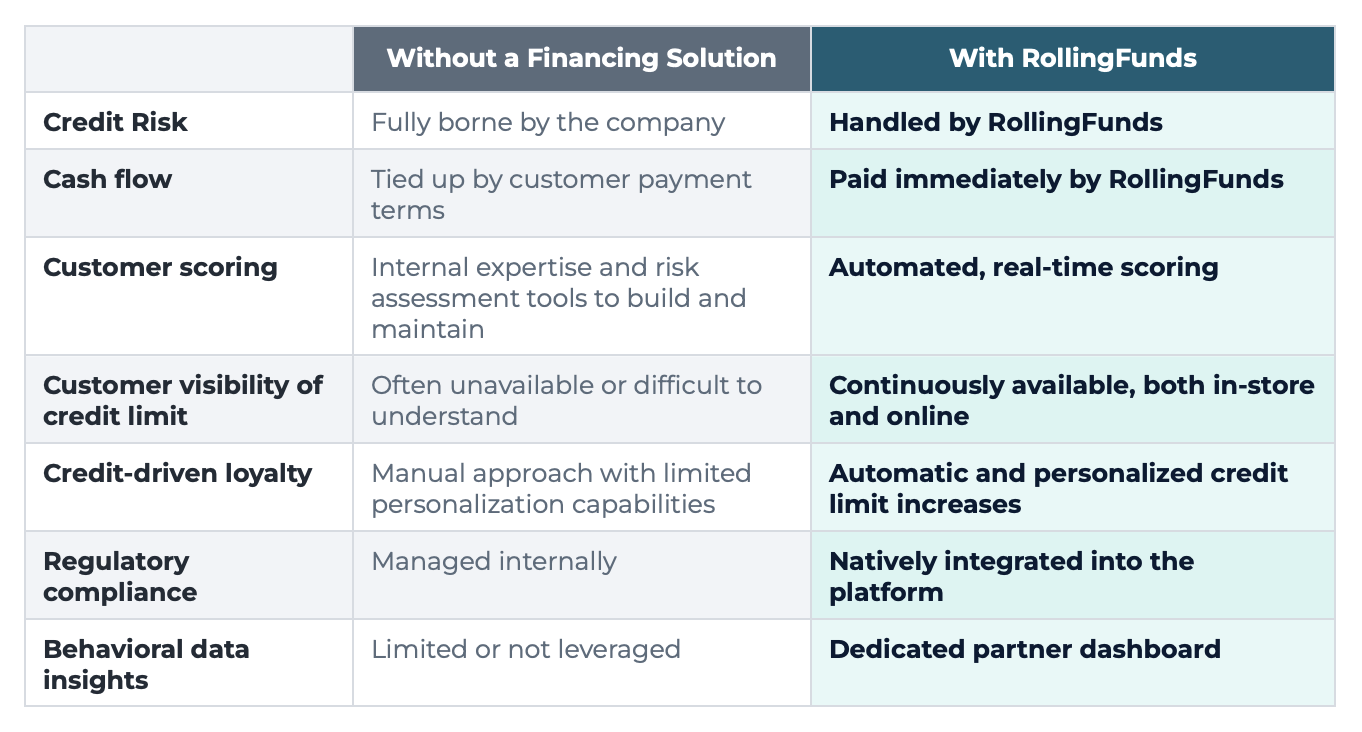
In summary, RollingFunds transforms a cash flow constraint into a sustainable commercial advantage: more trust, stronger customer loyalty, and increased sales—without adding complexity for your teams.
Conclusion: Turn Credit into a Competitive Advantage
B2B credit is no longer just a cash flow management tool—it has become a powerful lever for growth, customer loyalty, and differentiation. Suppliers, distributors, and B2B merchants that integrate credit into their broader commercial strategy can enhance the purchasing experience for their professional customers, increase sales, and build sustainable long-term growth.
RollingFunds was designed to make this strategy accessible to all partners, regardless of their size, without requiring them to assume credit risk or build in-house expertise in scoring, financing, and collections. By giving every professional customer a clear, personalized credit limit available exactly when needed, RollingFunds transforms financing into a natural purchasing habit—and a powerful reason for customers to return to your stores, e-commerce platform, or marketplace.
The objective is not to provide the highest possible amount of credit, but to offer the right financing capacity, to the right customer, at the right time. This is the balance RollingFunds manages on your behalf—turning credit into a driver of sustainable growth.