The success of Buy Now, Pay Later (BNPL) has transformed consumer shopping habits, driven by giants like Klarna and Amazon. In a world where credit reigns supreme, the ability to spread out payments is becoming increasingly attractive. It was only natural for businesses to seek to adopt this model. However, its integration into B2B has remained limited—until now.
Companies are now looking for more flexible solutions to finance their purchases and optimize their cash flow, a need that has been amplified by the rise of B2B e-commerce. The benefits are clear: sellers offering a BNPL option see a 15% to 40% increase in their conversion rates.
So, how does BNPL work in B2B, and how can a deferred payment solution become a strategic asset for your business?
B2B BNPL B2B: How is It Different from B2C BNPL?
Buy Now, Pay Later (BNPL) B2B allows businesses to purchase goods and services immediately while spreading payments over a defined period of time. Like its B2C counterpart, it provides an effective solution for smoothing expenses and improving cash flow. However, several key differences set it apart:
- Payment Terms In B2B, transaction amounts are higher, leading to longer payment terms and more complex conditions, whereas B2C operates on shorter and simpler repayment schedules.
- Decision-making process: In B2B, multiple stakeholders are involved in the purchasing process, unlike B2C, where decisions are made individually.
- Integration and payment methods: B2B BNPL integrates with accounting systems, CRM, and invoicing tools, offering a variety of payment methods, while B2C is primarily focused on standard payment options.
- Transaction fees: In B2B, fees may be charged to buyers, whereas in B2C, they are often covered by the sellers.
Some equate B2B BNPL to trade credit, but this comparison is oversimplified. Unlike traditional credit, which often comes with high interest rates and strict penalties, B2B BNPL offers more flexible terms tailored to business needs.
While its adoption has been slower due to implementation complexity, technological advancements and the emergence of specialized providers are now creating a strategic and profitable opportunity for businesses.
How Does B2B Buy Now, Pay Later (BNPL) Work?
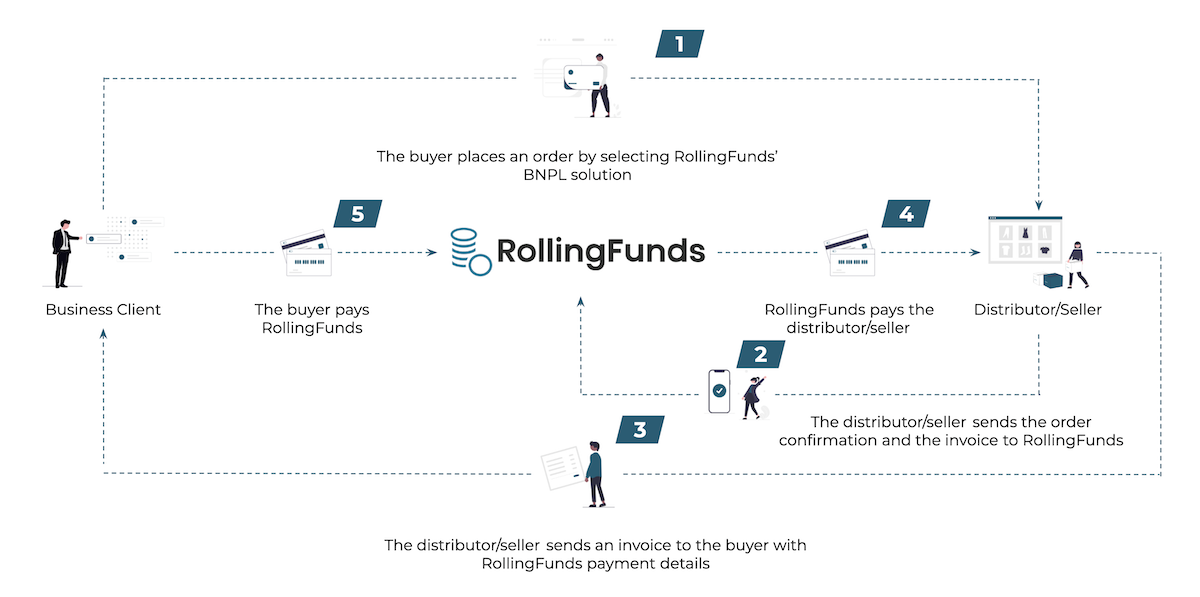
B2B BNPL simplifies and accelerates payments compared to traditional credit solutions. Here are the key steps of the process:
- Purchase: The business selects the products or services it needs and chooses BNPL at checkout.
- Approval: The BNPL provider quickly assesses the buyer’s creditworthiness and risk profile (including fraud risk) before approving the transaction.
- Installment payments: The total amount is divided into multiple installments or deferred over a set period of time (e.g., 30, 60 or 90 days for example).
- Completion: The buyer makes payments according to the agreed terms, while the seller receives the full amount immediately through the BNPL provider, ensuring a smooth and secure transaction.
How Does B2B BNPL Benefit Businesses and their Professional Clients?
More and more B2B companies are adopting Buy Now, Pay Later (BNPL), a solution that meets the needs of both buyers and sellers. Here are the key advantages:
For business clients
- Better Cash Flow Management
Spreading out payments prevents businesses from dipping into reserves or taking on loans. Instead, they can finance purchases using future revenue.
- More Flexibility to Invest
With deferred payments, companies can allocate their capital to growth, inventory, or other strategic opportunities.
- Less Financial Pressure
Distributing costs over time improves financial stability, allowing businesses to operate with greater confidence.
For Distributors/Sellers
- Higher Conversion Rates
Offering BNPL reduces cart abandonment and potential lost sales by 29%, according to Allianz, and can boost conversions by 15% to 40%. Customers are more likely to complete purchases with flexible payment terms.
- Increased Average Order Value (AOV)
Installment payments encourage buyers to place larger orders, knowing they have more time to pay.
- Stronger Customer Loyalty
BNPL fosters trust, both with new and existing customers, who appreciate the flexibility and the ability to use it repeatedly. A satisfied buyer is more likely to return.
While B2B BNPL creates a win-win dynamic, it is important to consider certain challenges and risks.
Key Challenges of B2B BNPL
While B2B Buy Now, Pay Later (BNPL) offers numerous advantages, its integration into business operations can be complex. Companies wishing to offer this solution must overcome several challenges.
- Cash Flow and Liquidity Management
Deferred payments are an advantage for buyers, but they can complicate the cash flow of sellers. Waiting several weeks, or even less, to receive payment can impact daily operations, inventory replenishment, and strategic investments, especially in industries where transactions are large in scale.
- Complexity of Credit Decisions
Assessing the creditworthiness of a business is much more delicate than in B2C. Transactions often involve large amounts, and a late payment or default can have major repercussions. The challenge is to find the balance between rigorous analysis and fast credit approval.
- Increased Administrative Load
In addition to credit checks, sellers need to manage customer accounts and track overdue payments. Without a dedicated team, these tasks can quickly become time-consuming and burdensome, especially for small businesses.
To overcome these challenges, it is possible to outsource BNPL management to a specialized provider like RollingFunds. The result:
- Sellers receive their payments immediately without managing the risks related to credit and unpaid invoices.
- Buyers benefit from flexible payment terms and receive their products faster.
One solution to tackle these challenges is to outsource the credit and operational risk of B2B BNPL to an external provider like RollingFunds. Buyers receive their goods faster and enjoy flexible payments, while their sellers receive full payment upfront without the hassle of managing credit checks and collections.
What is the Size of the BNPL Market in Europe and How is it evolving?
The Buy Now, Pay Later (BNPL) market in Europe is expected to reach €300 billion in 2025, capturing around 11% of the European e-commerce market, according to Deloitte. This growth is driven by the rapid adoption of BNPL by consumers, as well as the rise in demand for BNPL in the B2B sector. In fact, 80% of B2B customers now expect a payment experience similar to that of B2C. In other words, if a B2B company does not offer BNPL as a payment option, the risk of cart abandonment increases, representing a missed sales opportunity for the merchant.
Many companies are trying to meet this growing demand, but most current solutions have complex integration processes and low approval rates.
RollingFunds: A Solution That Stands Out
RollingFunds’ B2B BNPL solution stands out by offering a simple, smooth experience that is perfectly integrated into daily business operations. Its advantages include:
- A +30% increase in revenue generated by the B2B BNPL solution.
- Improved management of default risks (payment default rate <1%), ensuring better financing decisions and instant access to 100% of the funds.
- A fast UX with an instant funding approval decision. The experience is optimised to be addictive and repeatable (on average, a company uses the RollingFunds service 75 times a year).
- A variety of payment options, ranging from invoice payments (30, 60, and 90, or even 180 days) to installment payments (3 and 6 times), as well as access to a digital dashboard to centralize payments.
Additionally, features like automated reconciliation and payment offset simplify financial management, while integration with ERP, CRM, and PSP systems reduces setup time.
In summary, RollingFunds helps merchants save time and money so they can invest in their growth instead of in time-consuming administrative processes.
How RollingFunds’ B2B BNPL Payment Solutions Help Businesses Grow Safely
Offering B2B BNPL services is a strategic decision, but it is essential to do so securely, with a reliable system. RollingFunds’ deferred payment solution is designed to support businesses in this approach while reducing risks.
- Accelerate Credit Checks to Boost Sales and Limit Risk
Fast credit checks don’t necessarily mean more mistakes. RollingFunds offers quick and accurate assessments, minimizing the risk of late payments or defaults. With real-time checks, we guarantee a high approval rate, above 90%, which boosts your sales while reducing risks.
In case of payment default or insolvency, RollingFunds absorbs the loss, ensuring total security for you.
- Get Paid Instantly
Your customers have the ability to spread their payments over a period of time, but you don’t have to wait to receive your money. RollingFunds pays you immediately as soon as an order is confirmed. You receive your funds upfront, which you can use as working capital or for any other strategic opportunity.
- Reduce Administrative Burden
Administrative tasks can be time-consuming, especially when it comes to filing out forms or tracking overdue payments. RollingFunds simplifies your processes by handling follow-ups and collections. You no longer need to worry about managing overdue payments because you’ve already received full payment.
In summary, RollingFunds helps businesses grow safely by simplifying payment processes and eliminating financial and administrative risks.
How RollingFunds’ B2B Buy Now, Pay Later Solution Increased the Average Order Size by 4.5 Times
RollingFunds helps businesses attract new customers and boost their B2B sales by offering flexible payment terms. A notable example is La Plateforme du Bâtiment, leader in the Wholesale Building Materials industry. The company was losing several orders each month due to long and unreliable credit verification processes.
Thanks to RollingFunds’ B2B BNPL solution, this issue was resolved. After a seamless integration into their order process, the company now has access to instant credit decisions, both for online and offline transactions. Additionally, RollingFunds assumed the risk of each purchase.
Customers appreciated the flexible payment options, such as 30-day net terms and installment payments, which led to a 4.5-fold increase in the average order size.
Fast, flexible, and risk-free, RollingFunds enables businesses like La Plateforme du Bâtiment to win new customers and drive sustainable growth through secure and upfront payments, perfectly integrated into their daily operations.


